
What’s bigger: airplanes or airlines?
Humanity has always wanted to fly. When the airplane emerged in the 1900s, it galvanized the world with the promise of that dream. For decades, aviation was synonymous with airplane manufacturing. Commercial flight barely existed. The infrastructure required to operate airplanes at scale - airports, avionics, scheduling systems - was largely locked away, owned by the largest customer: the government. Military pilots got to fly. The rest of the world admired flight from a distance.
Early aviation peaked during 1940s, reaching billions in output. When the war ended, most of the of military orders vanished, and the industry was forced to pivot. What followed was not just better airplanes, but a wave of infrastructure innovation: airlines, airports, air traffic control, pricing systems, travel agencies.
That infrastructure, not the airplane itself, is what turned flight from a marvel into a mass experience. Today, 9 out of 10 U.S. adults have flown in their lifetime. Airlines generate close to $1 trillion in annual revenue, almost three times the revenue of airplane manufacturers. Air travel creates an estimated $4-5 of economic value for every $1 spent on an airplane.
The airplane remained iconic.
We watch movies about Air Force One, not about Delta.
Yet the infrastructure became dominant.
AI today is aviation before the rise of commercial airlines.
In this analogy, humanity’s thirst for intelligent machines is the old dream of flight.
Models are the airplanes. Model training is airplane manufacturing.
Model inference - the entire operational and infrastructure stack required to run trained models to accomplish real tasks - is the airlines, airports, and traffic control.
Just like early aviation, AI today is defined by what is most visible. We talk about models because they are measurable and iconic. In popular discourse, AI is synonymous with model capability.
But value does not accrue where visibility is highest.
It accrues where systems solve real problems at scale.
This is where the hidden monopoly in AI lives - not in models, but in inference. A trained model like GPT 5.2 is an artifact. An application like ChatGPT that actually helps users accomplish tasks is a system. It takes the model and layers user context, retrieval, tool use, state management, and latency guarantees. These are not finishing touches. They are the core of what makes intelligence operational.
This is why ChatGPT feels magical while an average application built on the same GPT 5.2 does not. The economic moat is not the model alone. It is the inference stack wrapped around it.
Inference is harder than we realize because it needs data.
We all know that models need data during training. Training data is difficult to produce, but it is also static, backward-looking, interchangeable, and increasingly commoditized.
But models are not software. They also need data during inference. And that data presents the next level challenge:
Real tasks require speed and personalization. Thus data must be contextual, proprietary, temporal, behavioral, and continuously refreshed. It must reflect who the user is, what they are doing right now, and how that relates to prior behavior.
Real tasks are also frequently mismatched with what the model was trained for. Making the model excel at a task it wasn’t built for requires golden data and continuous evaluation.
Solving this challenge will require the next level stack: data, metadata, semantics, systems of record, and infrastructure to move it around fast and at scale.
This complexity is why we see monthly (if not weekly) shifts in inference technology “required” to make a model useful. At first, it was prompt engineering. Then the industry moved to context engineering - which will take us a few years to digest. As structured context runs out, the bottleneck will shift to knowledge engineering.
We are nowhere near the inference investment required to automate the mundane.
Most of the inference stack is vertically integrated and siloed inside a handful of consumer applications and a small number of large enterprises that can afford to build full stacks themselves. The surface area exposed to the rest of the economy remains narrow. As a result, AI feels powerful in a few places and frustratingly limited everywhere else.
It is the aviation story all over again: big dream, iconic technology, underestimated infrastructure, and stunted value.
If history is any guide, the economics of AI will follow a similar curve. Airline operations grew to be almost three times larger than airplane manufacturing. To democratize AI - to make it fast, personalized, and useful across everyday work - investment in inference stack could easily exceed model training by a similar factor. This investment will produce new players, those that figured out how to scale AI-ready data. Like aviation, unlocking inference could create $4-5 in value for every $1 invested into the model.
It took aviation 75 years to unlock the value. Assuming AI time moves 10x faster, in 2032 the market could look like this:
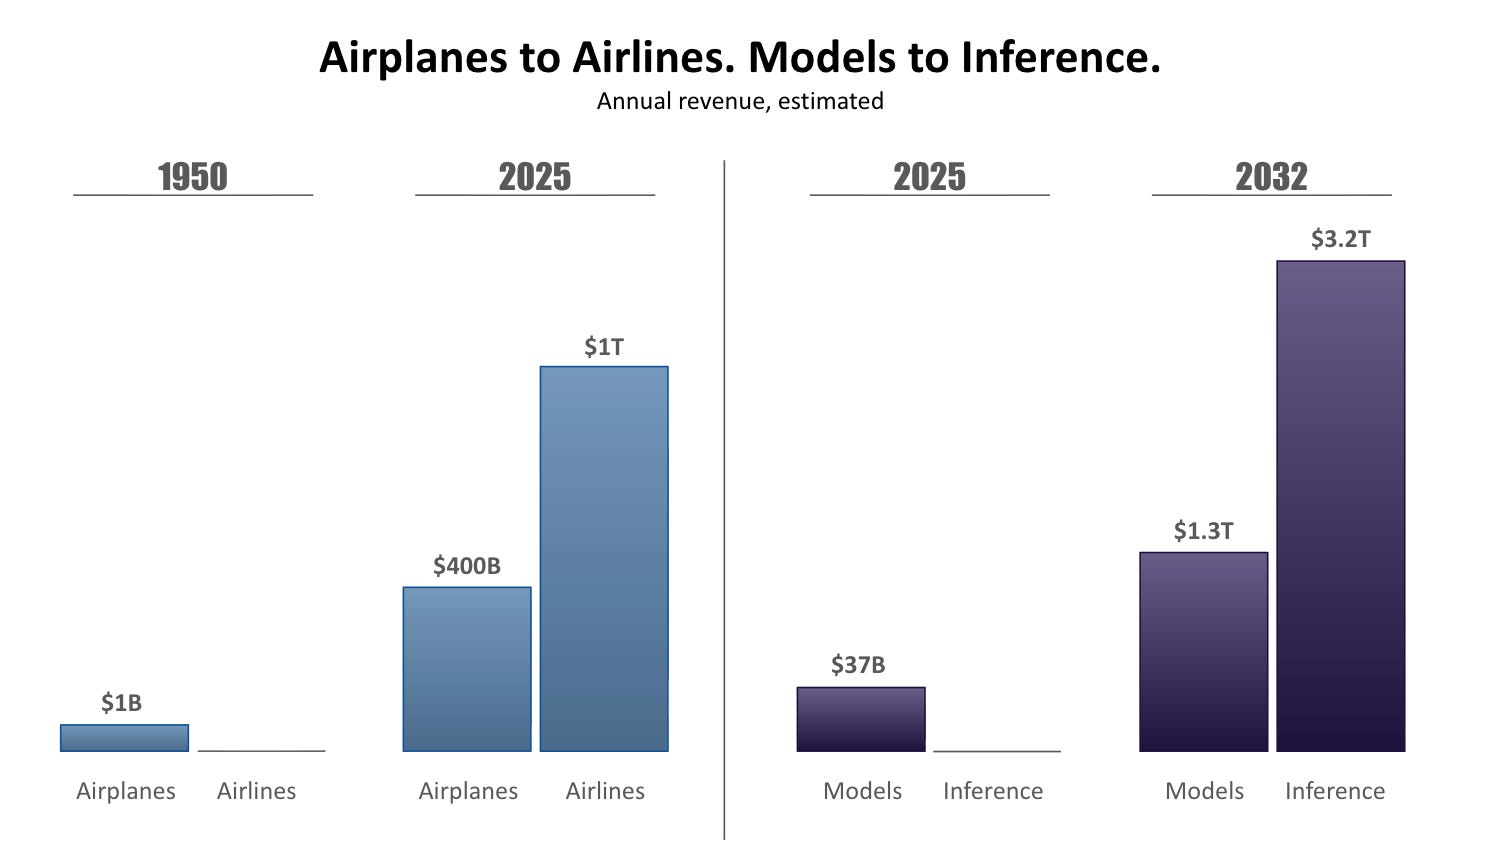
The implication is not that models do not matter. Airplanes still matter. They remain the symbol of flight. Models will remain the symbol of AI.
But inference - and data - is where most of the value will be created.
It may be a $3T industry in 7 years.
Sources:
$1B for airplane manufacturing revenue in 1950: Britannica “WWII in Aerospace industry“
$400B for airplane manufacturing revenue in 2025: IBISWorld report
$1T for airline revenue in 2025: IATA
$37B for model market in 2025: Menlo Ventures “2025: The State of Generative AI in the Enterprise”
$1.3T for model market in 2032: Bloomberg Intelligence (also consistent with the 400x airplane manufacturing growth)